A business can look extremely successful from the outside and still be short of money.
The phone rings.
Orders are coming in.
The diary is full.
Staff are busy.
Invoices are being raised.
The owner barely has time to answer emails because there is so much work.
Then payroll approaches and the bank balance looks alarmingly small.
This situation feels contradictory because busyness is often used as evidence of success. In everyday language, a busy restaurant, full tradesperson or booked-out consultant sounds like a healthy business.
Demand is certainly a good sign.
It is not the same thing as profitability or cash.
A business can be busy and broke when the work does not produce enough margin, when customers pay too slowly, when growth consumes cash or when the company is simply charging too little.
The first distinction is between revenue and profit.
Revenue tells you how much the business sells.
Profit tells you what remains after relevant costs.
A company can generate £500,000 of revenue and make very little profit if delivering that revenue costs almost £500,000.
This is obvious in theory and surprisingly easy to forget when sales are growing.
Large sales numbers create momentum.
The team feels productive.
Customers are buying.
It becomes tempting to assume that more revenue will solve financial pressure.
If margins are weak, more revenue can simply create more weak-margin work.
Imagine a business sells a service for £1,000.
Direct labour and materials cost £800.
That leaves £200 before rent, software, insurance, marketing, professional fees and other overhead.
If the company needs £300 of total contribution from each job to cover overhead and produce acceptable profit, every additional sale makes the team busier without fixing the economics.
Volume is not always the cure for pricing.
Sometimes the business needs to earn more from each unit of work.
Underpricing is one of the most common causes of unhealthy busyness.
New businesses often set prices low because they want to win customers.
That can be a useful launch strategy.
Problems arise when temporary introductory pricing becomes the permanent model.
Costs rise.
The owner becomes more experienced.
Service improves.
Demand increases.
But the price remains anchored to what felt necessary when the business was desperate for its first few customers.
Now the company fills its capacity at a rate that no longer makes sense.
The owner responds by working more hours.
This feels productive because the business is clearly in demand.
Financially, however, the company may be using labour to compensate for weak pricing.
There is a limit to how far that can go.
A person can work fifty hours.
Then sixty.
Then perhaps seventy for a period.
Eventually time runs out.
If profitability still depends on adding more owner hours, the business model has a problem.
Owner labour is particularly easy to undervalue.
Suppose a self-employed person completes a job for £400 after paying £100 of direct costs. They may think the job produced £300.
But if it required ten hours of skilled work plus two hours of administration, communication and travel, the economics need to recognise the owner's time.
The fact that the owner does not pay themselves an hourly wage for every task does not make those hours free.
A business should eventually generate enough value to compensate the people running it, not merely cover external bills.
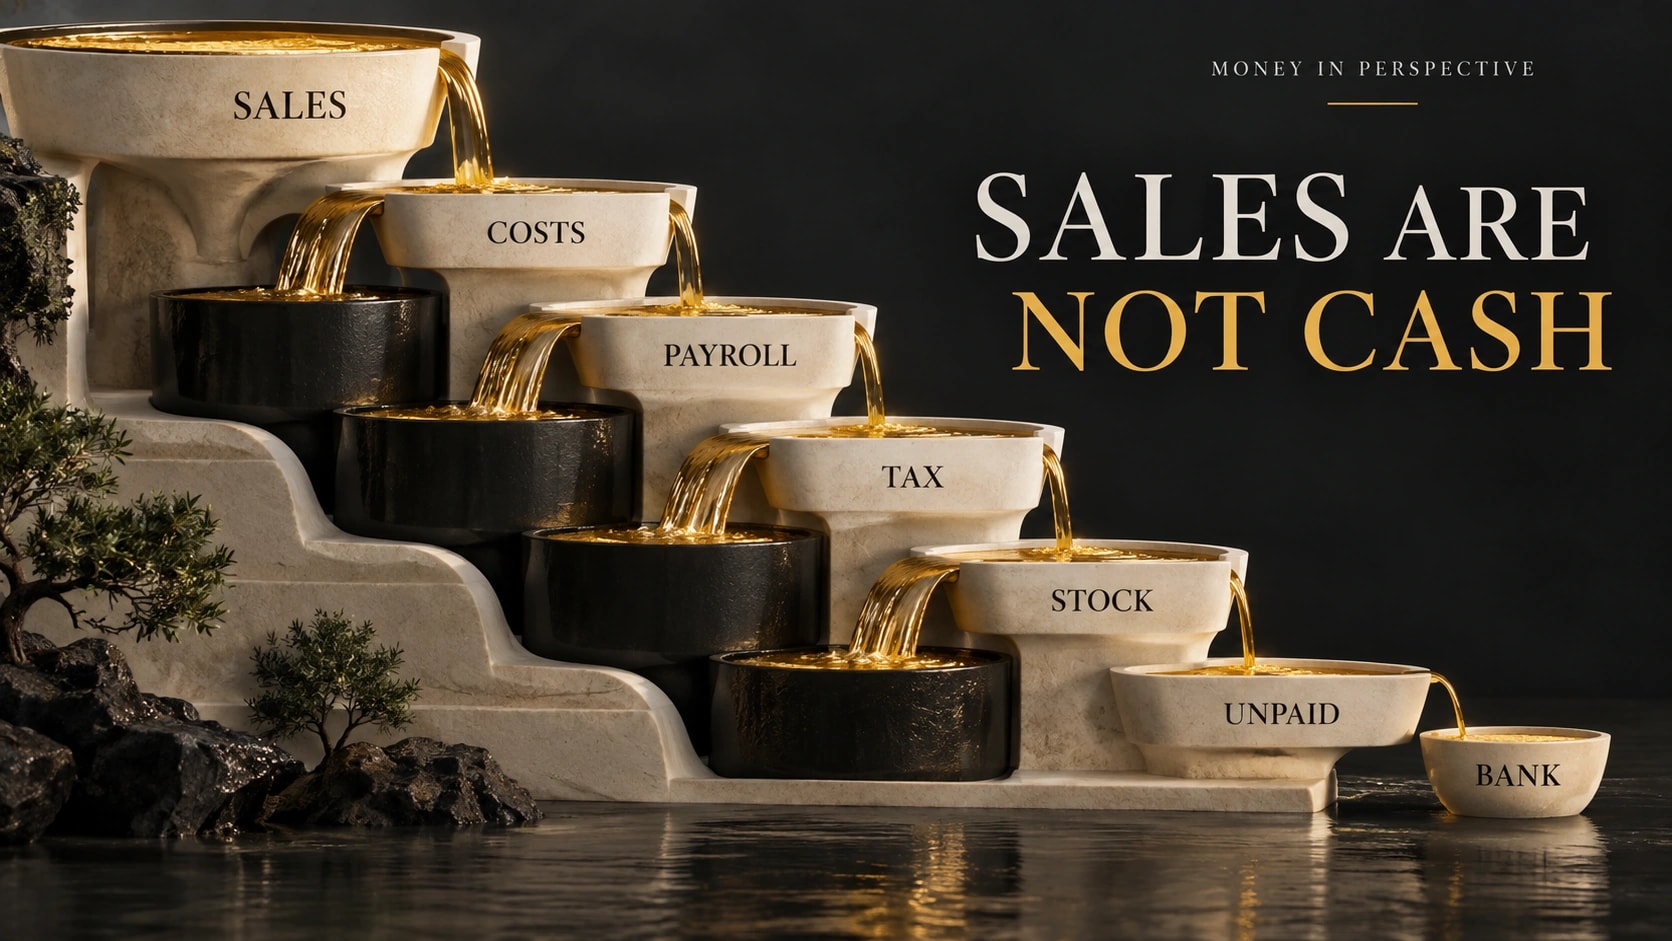
Cash flow creates another reason a busy company can feel broke.
The business may have made profitable sales but not received the money yet.
Customers have thirty-day terms.
Some pay in sixty.
The company has already paid staff, suppliers or subcontractors.
Now the profit exists on paper while the cash sits in trade debtors.
This is why a growing debtor balance deserves attention.
Sales are not complete from a cash-flow perspective until customers pay.
Credit control is therefore not an unpleasant administrative task sitting outside the “real” business.
It is part of turning work into usable money.
Invoice promptly.
Make payment terms clear.
Follow up overdue accounts.
Use deposits or staged payments where appropriate to the business model.
A company can improve cash flow significantly without selling one extra thing simply by collecting existing invoices faster.
Growth can make this timing problem worse.
Imagine a business wins twice as much work.
Excellent news.
To deliver it, the company hires staff, buys materials and pays suppliers.
Customers will pay in sixty days.
The business must fund the gap.
The faster it grows, the more cash it needs before the benefits of growth arrive.
This is why profitable businesses can fail during periods of rapid expansion.
They run out of cash while apparently doing well.
Working capital sounds like technical accounting language, but the concept is straightforward.
Money gets tied up in the operating cycle.
Stock.
Work in progress.
Unpaid invoices.
The business needs enough cash to keep operating while those assets eventually turn back into money.
Product businesses see this clearly with stock.
Buying inventory uses cash today.
Revenue arrives only when the items sell.
Too little stock can lose sales.
Too much stock can leave thousands of pounds sitting on shelves.
A warehouse full of products may look like business strength.
Financially, it may also be a bank account converted into boxes.
Slow-moving stock deserves particular attention because the money is trapped while the product may lose value or become obsolete.
Good inventory management is therefore part of cash management.
Tax creates another illusion.
VAT, payroll taxes and corporation tax can involve money sitting temporarily in the business account even though it has a future job.
If the owner looks only at the bank balance, this money can feel available.
Then the liability becomes due and the balance suddenly seems to collapse.
Setting aside expected tax can create a more honest picture of usable cash.
The same applies to annual bills and loan repayments.
A bank balance of £30,000 does not necessarily mean the business has £30,000 spare if £18,000 is already committed to obligations due soon.
Cash needs context.
Debt can hide weak economics for a while too.
Loans and credit facilities can keep the business operating despite poor margins or slow collections.
Borrowing can be extremely useful for investment, growth or temporary working-capital needs.
It becomes dangerous when debt is repeatedly used to fund a business model that does not generate enough cash.
The loan fixes liquidity today while interest and repayments increase pressure tomorrow.
The key question is whether borrowing supports a profitable business or postpones the need to fix an unprofitable one.
Owner drawings or dividends can create another gap.
A profitable company may still become cash-poor if too much money is withdrawn before tax, working capital and future costs are funded.
Owners understandably want to benefit from the business they created.
The challenge is separating accounting profit from cash genuinely available for distribution.
This becomes especially important in seasonal businesses.
A company may have a very strong summer and need much of that cash to survive winter.
If the high-season bank balance is treated as permanent wealth, later months can become painful.
Forecasting helps.
A simple cash-flow forecast does not need to predict the future perfectly.
List expected receipts.
List payroll, rent, suppliers, tax, loan repayments and major purchases.
Project the balance over the coming weeks or months.
The value is not precision.
The value is warning.
A projected shortage eight weeks away gives the business time to collect debts, delay discretionary spending, arrange finance or adjust plans.
Discovering the shortage the morning payroll is due produces much worse options.
Busy businesses also need to understand capacity.
If every staff member is fully occupied, the business has reached an important point.
Adding more customers may require overtime, new staff or slower service.
Each option changes costs.
This means a full diary is not automatically a signal to sell more.
It may be a signal to increase prices, improve efficiency or change the mix of work.
When capacity is scarce, the business should ask which work deserves it most.
High-margin services.
Reliable customers.
Work that fits existing systems.
Work with strong repeat potential.
If the diary is filled with low-margin, complicated jobs, maximum utilisation can produce minimum satisfaction.
This is why revenue per employee, gross margin, contribution margin or other relevant measures can be more useful than raw sales alone.
The exact metric depends on the business.
The principle is to connect activity with financial output.
Vanity metrics can distract from this.
Website visits.
Followers.
Enquiries.
Orders.
Customers.
Revenue.
All can be useful.
None guarantees a healthy business.
Ten thousand followers who never buy are not the same as a profitable customer base.
A million pounds of revenue with no profit is not automatically better than £400,000 of revenue with strong margins and cash generation.
Scale can be impressive and fragile at the same time.
This is also why owners should know the break-even point.
Roughly how much gross profit or contribution does the business need each month to cover fixed costs?
Once you know that, sales targets become more meaningful.
A £50,000 revenue target sounds good.
A target based on the margin required to cover costs and generate desired profit is better.
Pricing decisions improve too.
Discounting a product by 10% does not necessarily reduce profit by 10%. If margins are already narrow, the effect can be much larger.
This is one reason discount-led growth can create extreme busyness with little financial reward.
The company wins work by reducing the very margin it needs.
Sometimes the correct strategy is fewer customers at better economics.
That can feel uncomfortable because a quieter business looks less successful.
But if staff are less stretched, customers receive better service and profit rises, the company is stronger.
Activity is not the objective.
Value creation is.
A healthy business should eventually produce several things at once:
good service for customers,
fair compensation for staff and owners,
cash for tax and obligations,
reserves for difficult periods,
and profit that justifies the risk of operating.
If one of these is permanently missing, busyness may be hiding a structural issue.
This does not mean every young business should be highly profitable immediately.
Start-ups invest.
Businesses have difficult years.
Growth requires spending.
Strategic periods of low profit can make sense.
The important thing is to understand whether the weak cash position is planned and temporary or simply unexplained.
A business owner should be able to answer:
Are we profitable?
Which services or products make money?
How quickly do customers pay?
What is our cash position after known liabilities?
How much working capital does growth require?
What happens if sales fall for two months?
These questions matter more than whether everyone looks busy.
There is a cultural issue here too.
Entrepreneurs are often praised for constant activity.
Long hours.
Packed calendars.
Endless orders.
“Booked out for months” sounds like success.
Sometimes it is.
Sometimes it means prices are too low.
If customers are queuing for a service and the owner cannot earn a sustainable income from delivering it, demand is not the main problem.
Economics are.
The best businesses are not necessarily the busiest.
They are the ones where activity converts into healthy cash and profit without destroying the people doing the work.
If your company is constantly busy and constantly short of money, do not automatically ask how to win more customers.
First ask where the money from the existing customers is going.
Look at price.
Margin.
Time.
Debtors.
Stock.
Tax.
Debt.
Owner withdrawals.
Growth costs.
The answer is usually somewhere in that system.
Busyness proves people want something from the business.
That is valuable.
The next job is making sure the business receives enough value in return.