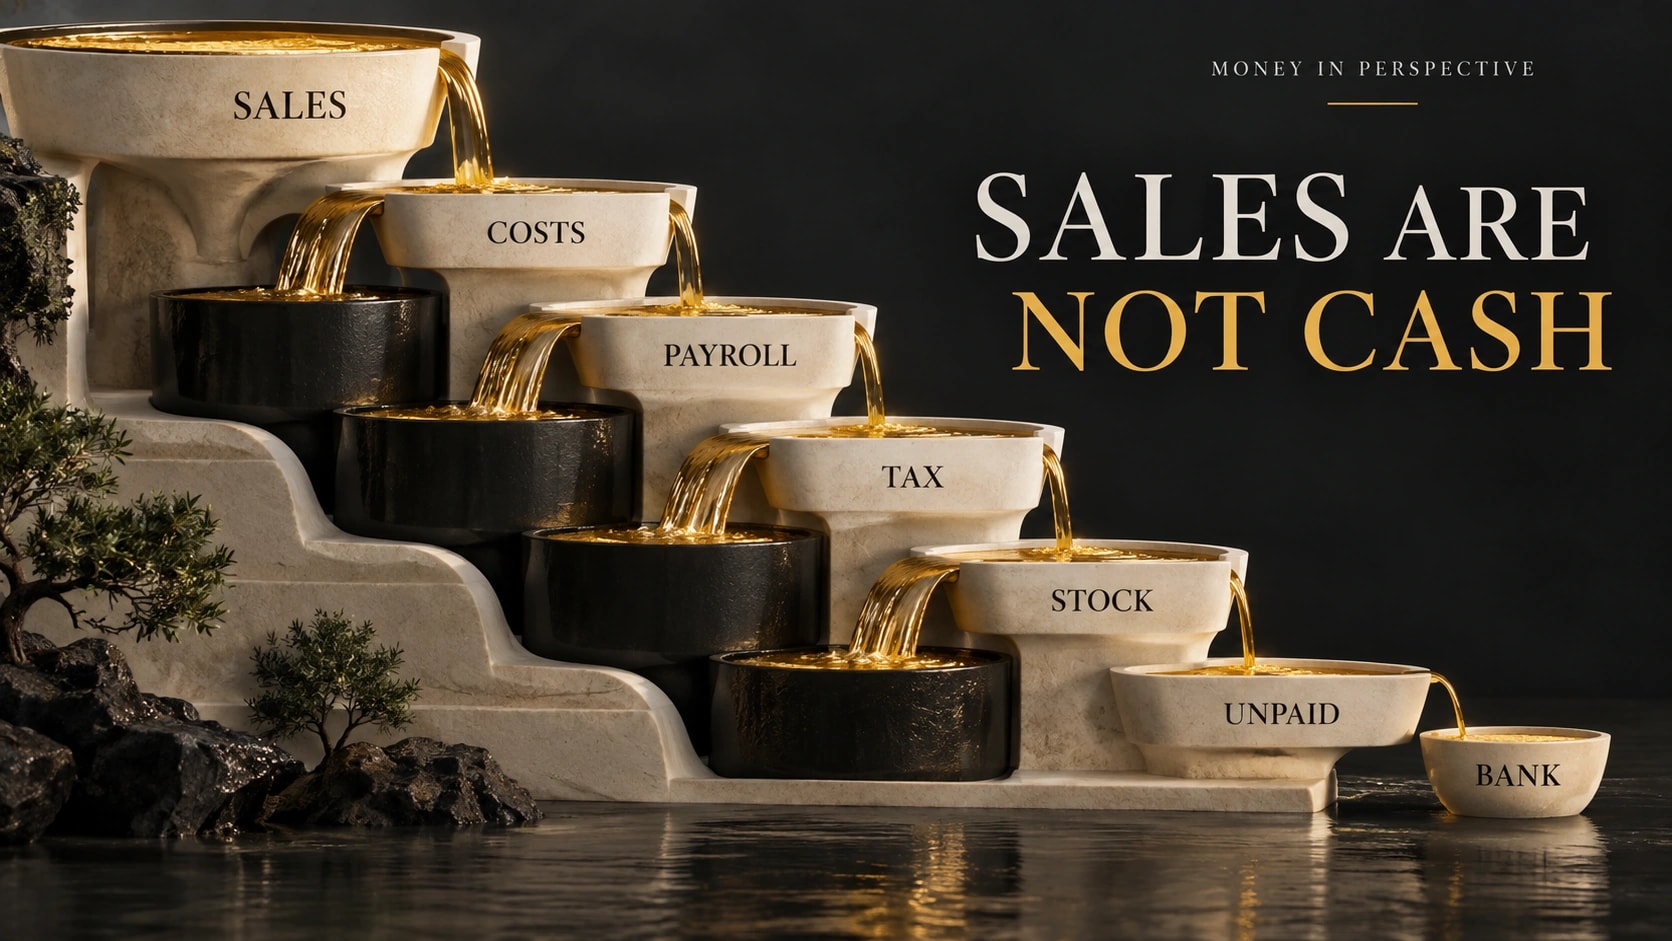
The sales report says £30,000. The bank balance says £7,000. Before you accuse either of lying, check whether they are answering the same question.
Revenue records what a business has earned from its trading activity. Cash records money received and paid. Between the two sit unpaid invoices, stock, equipment, borrowing and the calendar. A healthy sales month can leave very little room to pay next Friday’s wages.
The useful question is not simply “Are we profitable?” It is “Where is the profit sitting, and when can we spend it?”
Follow one month through the accounts
Illustrative worked example — not a real client case. A small wholesaler starts the month with £10,000 in cash. It has no opening customer debts or stock. It makes £30,000 of sales, all earned during the month, but receives only £24,000 before month-end. The remaining £6,000 is collectible next month.
It buys £18,000 of stock for cash. Goods costing £12,000 are sold; £6,000 remains on the shelves. It also pays £8,000 of operating costs and buys £6,000 of equipment. Total depreciation for the month is £1,000. Finally, it receives a £5,000 business loan.
For clarity, this example excludes VAT, tax, interest, owner withdrawals and opening liabilities. Assume no other transactions or adjustments. Those exclusions would need adding in a real forecast.
| Profit calculation | Amount |
|---|---|
| Revenue earned | £30,000 |
| Cost of stock sold | −£12,000 |
| Operating expenses | −£8,000 |
| Depreciation | −£1,000 |
| Accounting profit before tax and interest | £9,000 |
Now watch the bank account.
| Cash calculation | Amount |
|---|---|
| Opening cash | £10,000 |
| Customer receipts | +£24,000 |
| Stock purchases paid | −£18,000 |
| Operating costs paid | −£8,000 |
| Equipment paid for | −£6,000 |
| Loan received | +£5,000 |
| Closing cash | £7,000 |
The business earned £9,000 of profit while its cash fell by £3,000. Neither number contradicts the other. The profit calculation charges the stock actually sold and depreciation; the cash calculation records what physically went through the bank.
Build the bridge, rather than guessing
A reconciliation explains every pound of the difference:
£10,000 opening cash + £9,000 profit + £1,000 depreciation − £6,000 increase in customer debts − £6,000 increase in stock − £6,000 equipment purchase + £5,000 borrowing = £7,000 closing cash.
Depreciation is added back because it reduced profit without taking cash out this month. Buying equipment did take cash out, but its entire purchase price was not an operating expense in this profit calculation. Borrowing increased cash without becoming revenue. It also created a repayment obligation; it is not a free improvement in performance.
This is why “sales less whatever left the bank” is not an adequate profit calculation. It can mistake a loan for success and a stock purchase for a loss.
Growth can make the gap wider
Suppose next month’s orders require another £4,000 of stock before customers pay their £6,000 outstanding balance. The bank balance can briefly fall to £3,000 even if collection later restores it to £9,000. A month-end total would hide that squeeze.
ACCA’s working-capital guide explains the cash operating cycle through inventory, receivables and payables. The practical point is timing: how long money is committed before customers return it, and how much supplier credit genuinely helps fund that interval.
For this wholesaler, the first intervention might be collecting the £6,000 promptly, not selling another £6,000 on the same slow terms. More orders could require more stock and deepen the immediate gap. Discounting to win those orders might make both the margin and the financing problem worse.
That does not make growth undesirable. It makes growth something to fund.
Make a forecast that shows the uncomfortable week
Start with cleared cash. Put expected receipts into the weeks they are realistically likely to arrive, rather than copying invoice dates. Add wages, supplier payments, VAT or tax when applicable, loan repayments and planned equipment purchases. Keep owner drawings visible as their own line.
Then produce a second version in which the largest expected receipt arrives two weeks late. If one delay makes payroll impossible, the forecast has discovered something useful before the bank does.
A practical review should distinguish:
- Collection: which invoices are due, disputed or already overdue?
- Stock: which purchases support near-term orders, and which merely make the shelves reassuringly full?
- Commitments: what must be paid before the next reliable receipt?
- Funding: which facilities are actually agreed and available, rather than hoped for?
Do not solve a temporary gap by treating tax reserves or customer deposits as spare profit. Nor should an unexplained balance be labelled safe to withdraw just because it appears in the banking app.
The example’s £7,000 is a starting point for those questions, not a verdict that the business is healthy or failing. Once the cash bridge is clear, the next decision becomes specific: collect, reduce stock, reschedule an optional purchase or arrange suitable funding. “Sell more” is no longer the only answer on the page.